By Gopavajhala Diwakar
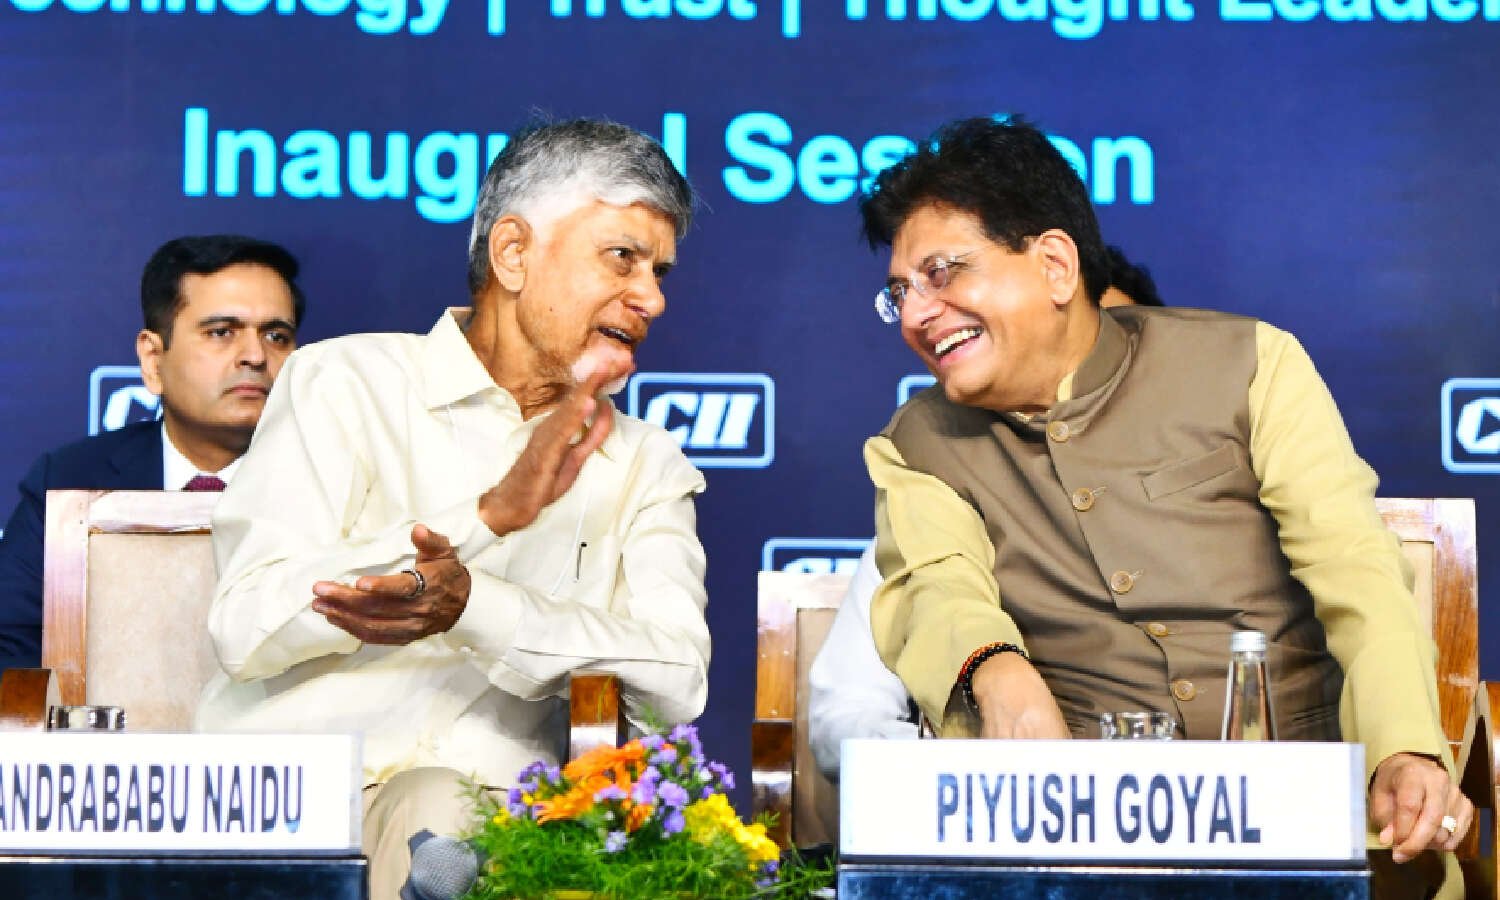
At the CII investors summit in Visakhapatnam on November 12, Chief Minister N Chandrababu Naidu announced that the state would bring an Investment Protection Act to safeguard investors from regime changes and political vendetta.
The stated aim is that incentives, land allotments and approvals granted to investors cannot be reversed by future administrations. He has also asked the Centre to enact a similar law nationally. No draft is public yet, so any assessment rests on the announced intent.
What the state can legally do
Industrial promotion, state land and state-granted incentives fall within the state’s own domain. The state is legislating about its own commitments, so the Act is within legislative competence.
Why a law can’t bind the next assembly
A legislature cannot bind its successors. A future assembly can amend or repeal the Act by ordinary legislation, so the Act cannot guarantee permanence. At best it can raise the cost and difficulty of reversal, for example by:
- requiring compensation when a commitment is withdrawn
- requiring a judicial or independent process before any reversal
- defining which grants are protected and for how long.
What courts already provide
Promissory estoppel and legitimate expectation already let investors challenge arbitrary reversals. Courts also allow governments to change course where the public interest requires it. A statute could narrow that room, but how far depends on its wording. A tightly drafted Act could add certainty. A vaguely drafted one adds little to existing doctrine.
Limits from higher law
The state cannot override central laws, such as those on electricity and environmental clearances, and cannot grant rights that conflict with the Constitution. Protection would cover state-granted benefits, not approvals that depend on central authorities.
The competing view
Critics could argue that shielding all past grants from review also shields flawed or corrupt ones, and that a government elected to change policy should not be locked in by its predecessor. Supporters would respond that credibility on commitments is what attracts long-gestation investment, and that compensation-based safeguards, rather than outright bans on reversal, address both concerns.
The contractor test
There is a local yardstick for credibility. In both Telugu states, contractors who carried out works under one government have long complained of delayed or unpaid bills under the next.
Strictly, a contractor is a supplier of services, not an investor, and pending bills are often a cash-flow problem rather than a policy reversal. Still, the underlying question is the same: does a sovereign honour an agreement made by its predecessor? The Act as announced focuses on investors, incentives and land, so it would probably not cover contractors. Whether it should is a fair question to put to the government.
Conclusion
The Act is legally feasible, but it cannot deliver absolute protection. Its value will depend on enforceable remedies, such as compensation and independent adjudication, and on whether successive governments accept it. A political consensus would matter as much as the statute. Investors will also judge the state by how it treats dues inherited from earlier regimes, since that is the clearest evidence of whether commitments survive a change of government.
If the Central Government were to enact a similar law at the national level, it could potentially provide a more uniform framework for investment protection across states. However, even a central law cannot permanently prevent a future Parliament from amending or repealing it.
Ultimately, whether at the state or national level, the credibility of such legislation will depend not merely on its legal provisions but also on the political consensus behind it and the willingness of successive governments to honour commitments made by their predecessors.